A2A Payments vs Card Networks
A comprehensive comparison of modern Account-to-Account payments versus traditional card network infrastructure
At a glance
| Feature | payware (A2A) | Card Networks |
|---|---|---|
| Transaction Fee | 0.5% | 2-3% |
| Fixed Per-Transaction Fee | $0.00 | $0.10-$0.30 |
| Settlement Time | Instant | 2-3 days |
| Chargeback Risk | Minimal | High |
| PCI Compliance Required | No | Yes |
| Hardware Required | No | Yes |
| Payment Initiation Methods | 7 methods | 1 method |
| International Standard | Open Standards | Proprietary |
Cost comparison by business size
Small Business
$20,000/month
Save $5,760/year
83% cost reduction
Medium Business
$100,000/month
Save $28,800/year
83% cost reduction
Enterprise
$1,000,000/month
Save $288,000/year
83% cost reduction
Why such a dramatic difference?
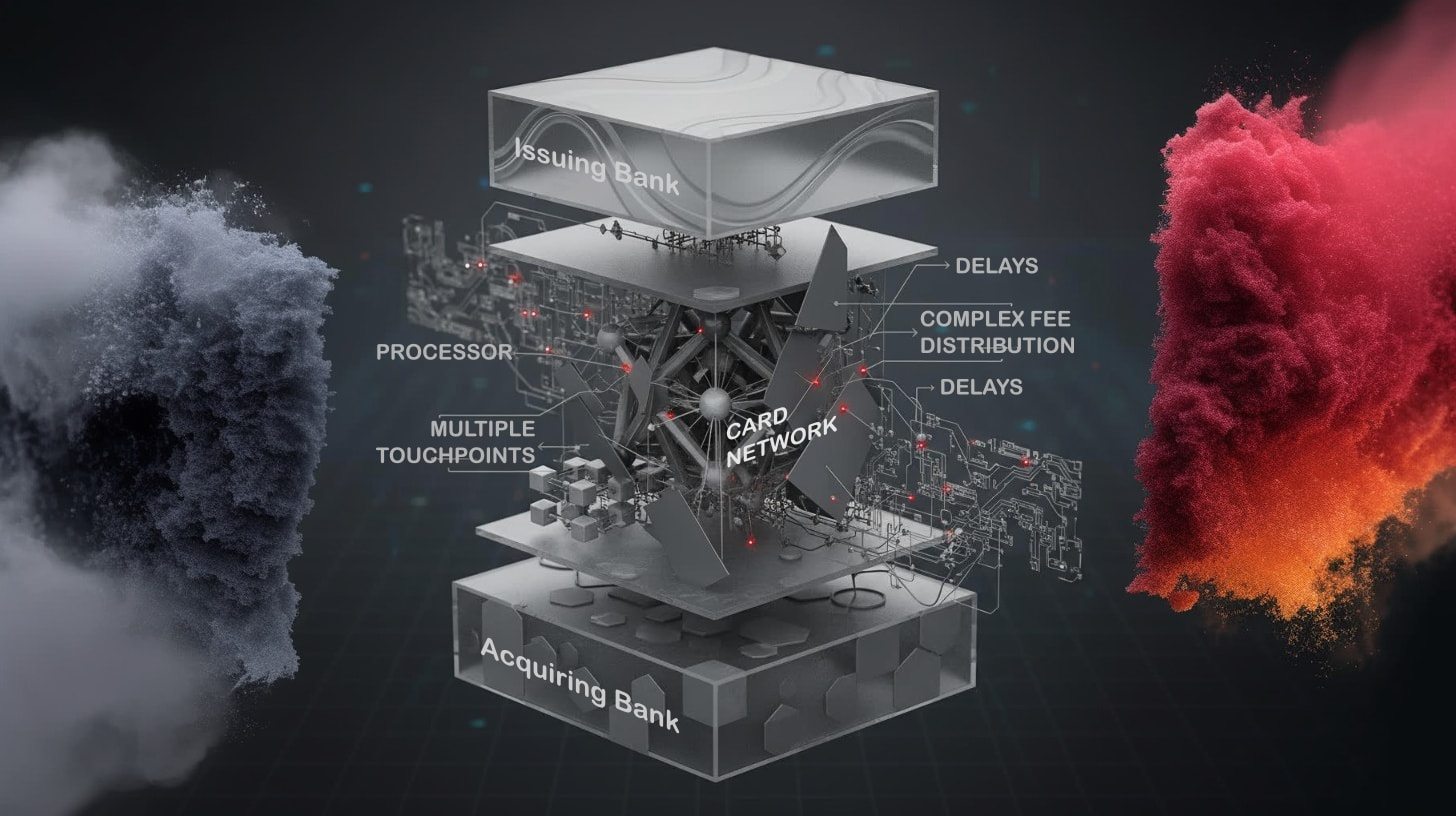
Card Network Path
Customer pays with card
Swipe, tap, or enter card details
Payment processor fee
First layer of fees (Stripe, Square, etc.)
Card network fee
Visa/Mastercard interchange fees
Issuing bank fee
Customer's bank takes a cut
Settlement (2-3 days)
You finally receive your money
Total Cost: 2-3% + fixed fees
Multiple intermediaries each taking a cut
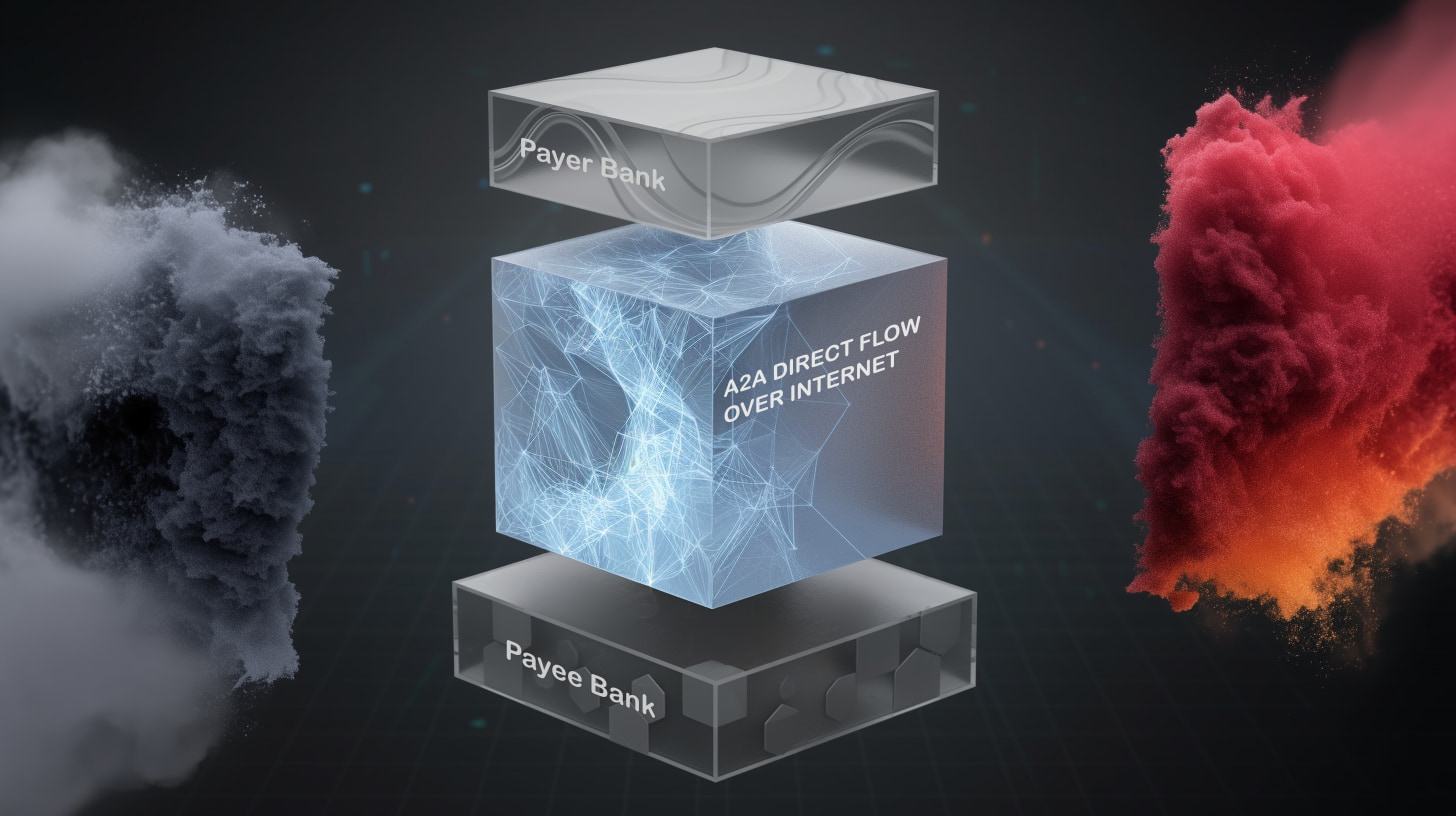
A2A Path (payware)
Customer initiates payment
QR, NFC, link, or any of 7 methods
Direct bank-to-bank transfer
Money moves directly between accounts
Instant settlement
You receive your money immediately
Total Cost: 0.5%
No intermediaries, no waiting (rates vary by region)
The bottom line: Eliminating intermediaries reduces costs by 95%+ while improving settlement times from days to seconds.
Beyond cost savings: New business models
A2A payments enable innovative revenue streams and business opportunities that traditional card networks cannot support
Revenue Sharing Models
Create partner ecosystems where ISVs, merchants, and payment institutions share transaction value - impossible with card network fee structures
Embedded Payment Platforms
ISVs can become payment facilitators with white-label solutions, earning recurring revenue from every transaction their platform processes
Instant Settlement Services
Build premium services around real-time money movement - merchants pay for instant access to funds, creating new revenue streams
Context-Aware Payments
7 initiation methods (QR, NFC, text, link, barcode, BLE, soundbite) enable payments in contexts where cards don't work - events, vending, transit, IoT
Multi-Sided Marketplace Revenue
Platform economics where payment institutions, ISVs, and merchants all participate in network growth - each new participant increases value for all
Data & Analytics Services
Lower transaction costs free up budget for value-added services - fraud detection, customer insights, financial reporting that generates recurring revenue
Break free from card network economics
Eliminate intermediaries, unlock instant settlement, and enable payment experiences cards can't deliver
Frequently Asked Questions
What are A2A (Account-to-Account) payments?
A2A payments are direct transfers between bank accounts without intermediaries like card networks. Money moves directly from the customer's bank to the merchant's bank, eliminating multiple fee layers and enabling instant settlement at significantly lower costs (as low as 0.5% vs 2-3%, rates vary by region).
How do A2A payments save 83% compared to card networks?
Card networks involve multiple intermediaries (processor, card network, issuing bank) that each take fees, totaling 2-3% plus fixed fees. A2A payments eliminate these intermediaries, using direct bank transfers starting from 0.5% with no fixed fees (rates vary by region), resulting in significant cost reduction.
Are A2A payments secure?
Yes, A2A payments use bank-level authentication and Strong Customer Authentication (SCA). Since money transfers directly between banks with real-time authorization, there's minimal chargeback risk compared to cards. No card data is stored or transmitted, eliminating PCI compliance requirements.
How do customers initiate A2A payments?
payware supports 7 payment initiation methods: QR codes, NFC contactless, text/SMS, payment links, barcodes, BLE (Bluetooth), and soundbite. This flexibility enables payments in contexts where cards don't work well, like events, vending machines, transit, and IoT devices.
Can I accept both A2A and card payments?
Absolutely! Many businesses offer A2A payments through payware for cost savings while maintaining card acceptance as a secondary option. Over time, most customers adopt A2A methods for convenience and speed, naturally shifting transaction volume to the lower-cost option.
Build the payment infrastructure your business deserves
Lower costs, faster money, more payment channels, zero chargebacks - all in one platform